 WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
Selling a property in India as an NRI or OCI holder isn't just a real estate transaction, it's a tax, FEMA, and cross-border compliance event rolled into one. Whether it's a residential flat, a commercial unit, something you inherited, a jointly owned property, or a straightforward investment sale, the transaction can trigger capital gains tax, TDS obligations, a Lower TDS Certificate application, FEMA compliance, DTAA considerations, repatriation procedures, and reporting requirements in both India and wherever you actually live.
Here's what we see constantly: NRIs losing lakhs of rupees to excessive TDS deductions, sitting through delayed refunds, working off incorrect capital gains numbers, tripping FEMA rules without realizing it, or simply missing tax-saving options they never knew existed. This is why proper planning is essential for NRI selling property in India, particularly where the transaction involves significant capital gains or repatriation of sale proceeds.
At Dinesh Aarjav & Associates, we handle it end to end for NRIs, OCIs, PIOs, Green Card holders, foreign citizens of Indian origin, and overseas Indians selling property in India. Whether you need assistance with NRI property sale in India, NRI selling land in India, Lower/Nil TDS Certificates, capital gains planning, FEMA compliance, repatriating the sale proceeds, DTAA advisory, the tax return itself, and the compliance that follows under the Income-tax Act, 2025, our team can assist throughout the transaction.
Twenty-five-plus years in this practice, offices in India, the US, UK, and Canada, and more than 10,500 NRI clients served globally. Our job is making sure the sale goes through cleanly and you keep as much of the proceeds as the law actually allows.
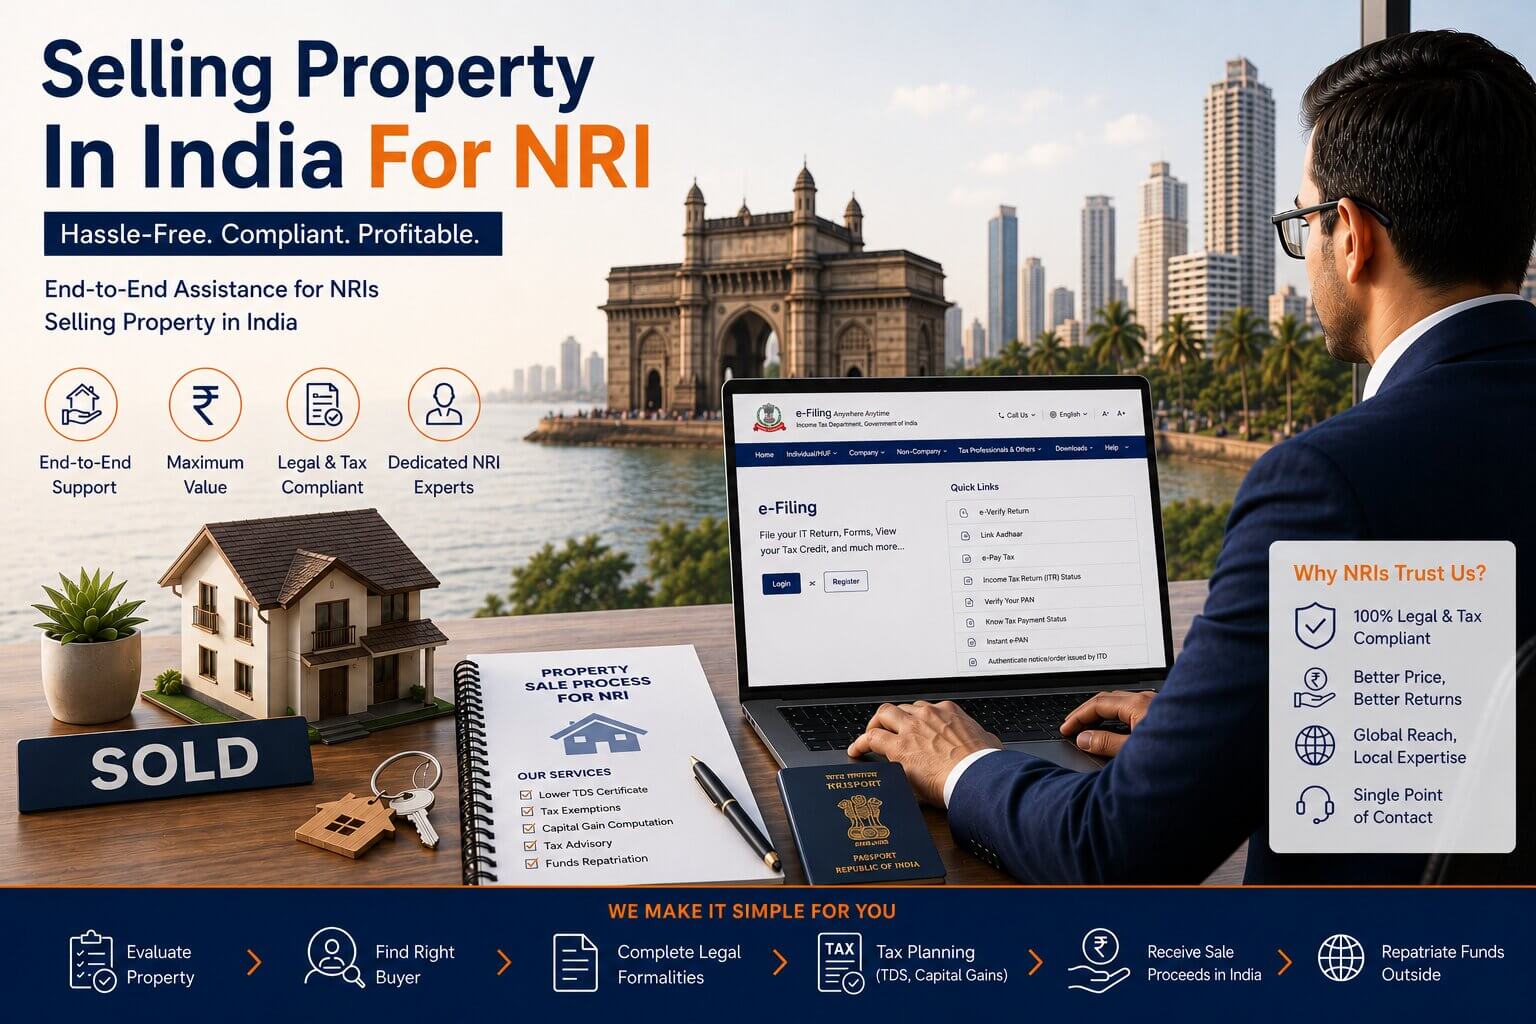
Resident Indians selling property don't deal with any of this. NRIs do, because special withholding provisions and FEMA regulations kick in the moment the seller isn't a resident.
A property sale as an NRI typically touches: TDS on the sale, the capital gains computation itself, a possible Lower/Nil TDS Certificate application, DTAA relief, FEMA compliance, getting the proceeds repatriated, NRO/NRE account planning, the specific rules around inherited property, joint ownership complications, a Power of Attorney if you can't be present, and reporting obligations wherever you're tax resident.
Skip the planning and you're looking at unnecessary tax withheld, funds sitting blocked for months, refunds that take forever to process, and compliance risks that were entirely avoidable
Here's where a lot of confusion creeps in. Most articles, legal opinions, property consultants, and YouTube explainers you'll find online still reference the old section numbers under the 1961 Act. For anyone planning a property sale in India by NRI, it is important to understand these updated provisions. The table below maps them to their equivalents under the Income-tax Act, 2025.
| Income Tax Act, 1961 | Income Tax Act, 2025 | Purpose |
|---|---|---|
| Section 195 | Section 393(2) | TDS on payments to Non-Residents |
| Section 197 | Section 395(1) | Lower / Nil TDS Certificate |
| Form 13 | Form 128 | Application for Lower TDS Certificate |
| Section 54 | Section 82 | Capital Gains Exemption – Residential House |
| Section 54EC | Section 85 | Capital Gains Exemption through Specified Bonds |
| Section 54F | Section 86 | Capital Gains Exemption through Reinvestment |
| Form 15CA | Form 145 | Foreign Remittance Declaration |
| Form 15CB | Form 146 | Chartered Accountant Certificate for Remittance |
Worth keeping this handy it'll save you from acting on outdated guidance while planning your sale.
For an NRI property sale, getting the tax calculation right is only one part of the process. We provide end-to-end support covering TDS, capital gains, Lower/Nil TDS Certificates, FEMA and RBI compliance, repatriation of sale proceeds, and DTAA advisory to help ensure your property sale is completed efficiently and in full compliance with applicable Indian tax and foreign exchange regulations.
The single biggest pain point for NRIs, OCI holders, and foreign residents selling property is TDS deducted on the gross sale price rather than on the actual gain which routinely exceeds real tax liability by a wide margin. Section 395(1) of the 2025 Act (Section 197 under the old law) lets eligible sellers apply for a Lower or Nil TDS Certificate via Form 128 (formerly Form 13), so tax gets withheld on estimated capital gains instead of the full sale value better cash flow, and one less refund to chase down later. We handle the capital gains computation, prepare the Form 128 application, review your documents, represent you before the Income Tax Department, and follow through until the certificate comes through.
This genuinely works better starting before you sign the sale agreement, not after. We work through long-term versus short-term capital gains, your original acquisition history, cost inflation index calculations, the specific rules for inherited or gifted property, joint ownership considerations, and how DTAA fits into the picture with the goal of legally minimizing what you owe while staying fully compliant.
Under Section 393(2) of the 2025 Act (Section 195 previously), the buyer is required to deduct tax before paying you. We help determine the correct TDS rate, review the buyer's compliance obligations, sort out TAN-related requirements, reconcile what's actually been deducted and deposited, and resolve disputes if the numbers don't add up, all of which leads to notices and penalties later.
Property sales by NRIs sit under FEMA and RBI regulation on top of the income tax rules. We verify ownership, review how the property was originally acquired, check FEMA eligibility, review RBI compliance, plan the repatriation route, and structure your NRO/NRE accounts correctly so the transaction closes smoothly and the funds actually move where they're supposed to.
For most NRIs, the whole point of the sale is getting the money back wherever you live. We prepare Form 145, certify Form 146, handle the FEMA paperwork, coordinate with the banks, plan the repatriation strategy, and put together the source-of-funds documentation aiming for a transfer that's smooth, timely, and fully compliant.
If you're in the US, Canada, UK, UAE, Singapore, Australia, New Zealand, or one of several European countries, you may well need to report this sale in your country of residence too. We handle foreign tax credit planning, work through double-taxation mitigation, help with capital gains reporting on the other side, and interpret the specific treaty provisions that apply so you're not paying tax twice on the same gain.
Under the earlier 1961 Act, TDS on property sold by an NRI was covered under Section 195; under the 2025 Act, this provision is now covered by Section 393(2). In either case, the buyer is required to deduct tax before making the payment to you.
Long-term capital gains apply if you've held the property for more than 24 months currently taxed at 12.5% plus surcharge and cess. Short-term capital gains apply for anything held 24 months or less, taxed at your applicable slab rate. In practice, though, buyers routinely deduct at a flat 30% plus surcharge and cess as a conservative default, simply because they have no visibility into your overall taxable income.
What actually determines the withholding: your residential status, whether the gain is long-term or short-term, whether you've secured a Lower TDS Certificate, any DTAA relief, and the applicable surcharge and cess. A common misconception is that TDS gets calculated only on the capital gain in reality, buyers deduct on the gross sale price unless you've already obtained a Lower TDS Certificate to redirect that.
The Lower TDS Certificate is arguably the single most valuable planning tool available to an NRI seller; it aligns what actually gets withheld with your real tax liability instead of the gross sale price. Under the 1961 Act this ran through Section 197 and Form 13; under the 2025 Act it's Section 395(1) and Form 128.
The upside is straightforward: less tax withheld at closing, better liquidity, a faster transaction close, and far less waiting around for a refund that shouldn't have been necessary in the first place.
Investing in specified capital gains bonds remains one of the more commonly used ways to claim exemption from long-term capital gains tax, subject to the usual conditions. This ran under Section 54EC previously; it's Section 85 now. Eligible options generally include NHAI bonds, REC bonds, and other notified capital gains bonds. The investment needs to happen within the prescribed window from the date of transfer missed that window and the exemption doesn't apply, so this is worth planning before the sale closes, not after.
If you reinvest the gains from selling a residential property into another qualifying residential property, within the specified timelines, you may be able to claim exemption that sat under Section 54 before, and is Section 82 now. It remains one of the most-used provisions for NRIs selling property in India, and structured properly, it can meaningfully cut down the overall tax bill.
Selling certain long-term capital assets and reinvesting the net sale consideration into a qualifying residential property can also open up an exemption Section 54F under the old law, Section 86 now. As with the other reinvestment routes, the benefit depends on meeting the prescribed conditions and timelines, so it's worth mapping out before you sign anything.
Banks and authorized dealers used to ask for Form 15CA and Form 15CB before processing an overseas remittance. Under the 2025 Act, those have been replaced by Form 145 and Form 146. Functionally, they do the same job supporting tax compliance and confirming the remittance is legitimate under both income tax and FEMA rules. We handle the documentation, the certifications, the FEMA side, and the bank coordination needed to get funds moved without unnecessary delay.
Whether you are selling from the USA, Canada, UK, UAE, Australia, or elsewhere, our cross-border advisory helps manage Indian tax, foreign reporting, DTAA, FEMA, TDS, and repatriation requirements.
NRIs in the USA often carry reporting obligations on both sides; we handle capital gains reporting, foreign tax credit planning, Form 1116 support, and FATCA/FBAR guidance alongside the Indian side of the transaction.
NRIs in Canada may need to report the sale to the CRA. We work through CRA reporting requirements, DTAA planning, and foreign tax credit strategy to keep the tax bill from doubling up.
NRIs in the UK frequently need to report the gain to HMRC. We support HMRC reporting, apply the India-UK DTAA, and plan foreign tax credits accordingly.
NRIs in the UAE usually need Indian-side guidance specifically, since UAE doesn't tax personal income. Our focus there is Indian tax planning, FEMA compliance, and getting the repatriation right.
NRIs in Australia typically carry reporting obligations in both countries. We handle the cross-border planning, foreign tax credit optimization, and DTAA advisory needed to avoid double taxation.
OCI card holders face largely the same rules as NRIs but with a few extra wrinkles around FEMA and residency status worth checking we cover the full range from tax planning through Lower TDS Certificates to remittance documentation.
The most common pattern is that the focus goes entirely into finding a buyer and closing the deal, while tax and compliance planning becomes an afterthought. This usually shows up as:
Planning before you start the sale process, not after the agreement is signed, is what actually protects your tax position, your cash flow, and how smoothly the funds move once the deal closes.
Twenty-five-plus years in this practice, more than 10,500 NRI clients globally, offices in India, the US, UK, and Canada, and a team built specifically around NRI tax Chartered Accountants, CPAs, and ACCAs with real depth in DTAA and FEMA, not generalist advisors bolting on cross-border work. We handle the property sale start to finish: Lower TDS Certificate work, capital gains planning, FEMA compliance, and the repatriation itself.
Our Chartered Accountants get quoted regularly on NRI taxation, FEMA compliance, property sale tax, and cross-border planning. A few recent mentions:
You're a resident of India if your stay in a given financial year is 182 days or more, or 60 days or more combined with 365 days or more across the four preceding years. If neither condition is met, you're an NRI.
Once your gross total income received in India exceeds Rs 2.5 lakh in a financial year, filing is required generally due by July 31 of the assessment year, unless extended by the government.
Rental income in India needs to be reported on your Indian return under your PAN, with tax paid accordingly. One property held for personal use counts as self-occupied; a second property, even if it's not actually let out, is treated as "deemed rented" and taxed on that basis, though you can claim 30% of the deemed rental as a maintenance deduction. There's usually no tax owed abroad on this deemed income, but declaring it properly matters when you later repatriate funds from India.
Yes, in principle India taxes it as the source country, and your country of residence can tax it too as the residence country. India's DTAA network exists precisely to prevent that double hit, typically by letting you claim credit for the foreign tax already paid.
No it applies to anyone earning income in India, resident or not.
Residents are taxed on global income in India. Non-residents are taxed only on income earned in India or sourced from an Indian activity.
Yes, dividends from Indian companies are taxed in shareholders' hands at 20%, without deductions under any provision of the Income Tax Act.
You can authorize someone via Power of Attorney to file on your behalf; a copy of the POA needs to accompany the return.
Yes, if your expected tax liability for the year exceeds Rs 10,000 missing it brings interest under Sections 234B and 234C.
Yes for property other than agricultural land, a farmhouse, or plantation property, the Authorised Dealer will allow repatriation of the sale proceeds, provided the property was originally acquired in accordance with the foreign exchange law that applied at the time, or under the current regulations.
Yes through a Power of Attorney executed in favor of someone in India. It needs to be legalized and apostilled in your home country, then registered in the state where the property is located.
Yes under Section 393(2) of the Income-tax Act, 2025 (formerly Section 195 of the 1961 Act).
Yes under Section 395(1), applied for via Form 128 (formerly Section 197 and Form 13).
Yes, potentially under Sections 82, 85, and 86, subject to meeting the eligibility conditions for each.
Yes, subject to FEMA regulations and standard banking requirements.
Yes capital gains tax generally applies, though special computation rules can come into play depending on the facts.
Yes, using a properly executed Power of Attorney.
Broadly yes, though FEMA and residency-related considerations are worth reviewing on a case-by-case basis.
We regularly work with NRIs and OCIs based in the USA, Canada, UK, UAE, Singapore, Australia, New Zealand, and Europe.
FCA, B.Com (H)
MBA (Int'l Banking & Finance), LLB, B. Com (H)
ACA, CISA, B. Com (H)
FCA, B.Com (H)
FCA, B.Com (H)
CA, B.Com
FCA, B.Com (H)

MBA (Int'l Banking & Finance), LLB, B. Com (H)
ACA, CISA, B. Com (H)
FCA, B.Com (H)
FCA, B.Com (H)
CA, B.Com
An Experienced Chartered Accountant with over 5 years of expertise in cross-border taxation, NRI taxation, and US tax compliances. She has extensive exposure in handling complex international tax matters, including India-US taxation, DTAA advisory, foreign disclosures, expatriate taxation, and tax planning for NRIs and returning Indians.
She is a Chartered Accountant and a Commerce Graduate, with strong proficiency in US tax filings and global tax advisory services.
.webp)


